What California Personal Injury Attorneys Should Know About Trust Accounting

Nettie Roos • March 21, 2026

Share this article

What California Personal Injury Attorneys Should Know About Trust Accounting

California Personal Injury Attorneys: When Your Trust Account Doesn’t Match, Start Here

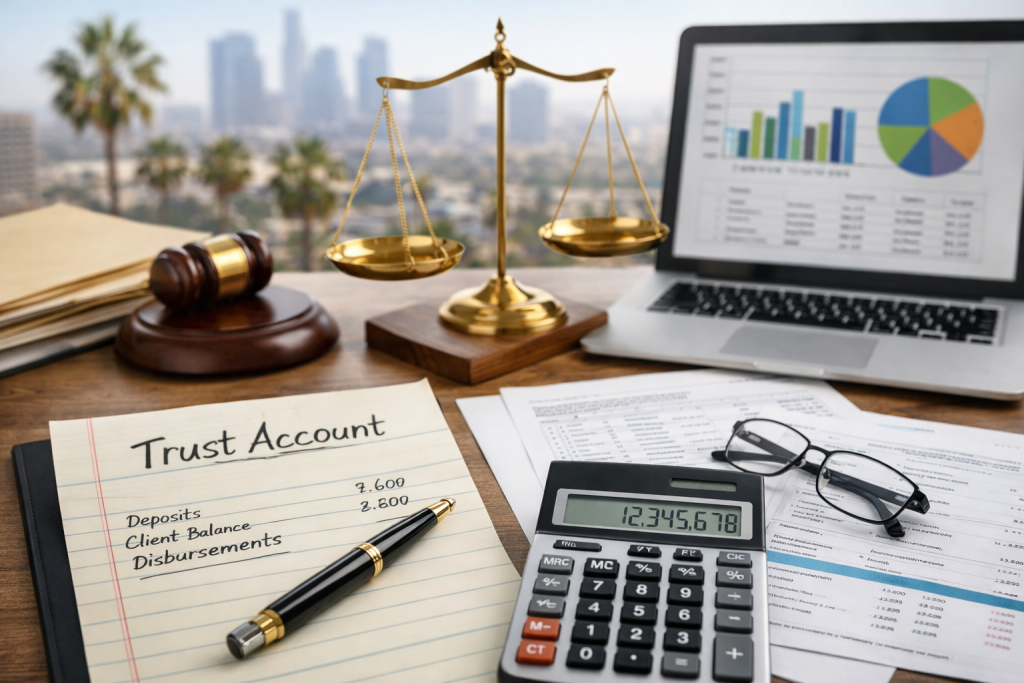
Most California personal injury attorneys don’t think much about their trust account until something stops matching. Usually it starts when the numbers in the accounting software don’t match the numbers in the case management system, or the trust account won’t reconcile and no one is quite sure why.

This is extremely common in personal injury firms because settlement accounting is more complicated than most people expect. Settlement funds move through the trust account, then get split between attorney fees, clients, medical providers, costs, and liens. If even one part of that process is recorded incorrectly, the trust balance and client ledgers slowly stop matching over time.


When Trust Accounts Don’t Reconcile

When a trust account doesn’t reconcile, it usually means one of three things happened. A deposit may have been recorded incorrectly, a settlement disbursement may have been entered wrong, or an old transaction was never cleared properly. Sometimes the issue is recent, but many times the problem actually started months or even years earlier and slowly built up.

Many firms first notice the problem when their accountant asks questions, when preparing for taxes, or when working through compliance or trust reporting requirements. By that point, it can be difficult to determine where the difference started. The worst time to notice the problem is when the bar is asking questions. At that point things are even more serious and your license is on the line.


Why This Happens in Personal Injury Firms

Personal injury firms handle more settlement money in unique ways from other practice areas. Each settlement often involves multiple parties, multiple payments, and requires careful tracking through the trust account and case management. If the workflow between the case management system and the accounting system is not set up correctly, the two systems slowly stop matching.

This is not usually because someone did something intentionally wrong. It is usually because the firm grew, the number of settlements increased, and the financial systems and processes did not grow with the firm. Over time, small inconsistencies turn into large reconciliation problems.


Where to Start If Your Trust Account Is Off

If you are trying to figure out whether your trust account is correct, start by comparing four numbers: the trust bank account balance, the trust ledger balance in your accounting system, the trust liability balance in your accounting system and the total of all client trust balances in your case management system. Those four numbers should match. If they do not match, the issue is usually related to a deposit, a disbursement, or an old uncleared transaction.

In some cases, firms can track this down internally. In other cases, the history has become complicated enough that the trust account needs to be rebuilt and reconciled step by step to bring everything back into balance.


When It’s Time to Get Help

Many personal injury firms try to fix trust accounting issues internally first, which makes sense. But when the issue involves older transactions, settlement accounting errors, or differences between the accounting system and case management system, it can take a significant amount of time to trace everything back and correct it properly.

This is usually when firms look for help from someone who specializes in legal bookkeeping, IOLTA management, and law firm financial operations. Personal injury firms in particular need systems that handle settlement accounting, trust tracking, and financial reporting correctly so these issues do not keep happening in the future.

If you are a California personal injury attorney and your trust account doesn’t reconcile, your accounting software and case management system don’t match, or you are not completely confident your trust accounting is correct, those are exactly the types of problems we help law firms work through and fix. You can contact us here to schedule a time to talk about your firm.

We specialize in legal bookkeeping, IOLTA management, and law firm operations. You can learn more about our services on our home page .

Recent Posts

By Nettie Roos • September 22, 2026
A practical new hire onboarding checklist for small business owners: paperwork, first week structure, ownership, and the 30/60/90 day check ins.
By Nettie Roos • September 22, 2026
What actually has to be documented before you can leave your business for two weeks: the bottleneck decisions, a simple SOP, and who decides while you're gone.
A business owner comparing a printed profit and loss statement to their bank account balance on a ph
By Nettie Roos • September 22, 2026
A profitable month can still leave your bank account looking scary. Here is why cash flow and profit disagree, and a simple way to track both every month.
By Nettie Roos • September 22, 2026
Learn the real signs you are underpricing your business, a simple way to check your price against true cost, and how to raise rates without losing clients.
By Nettie Roos • September 16, 2026
Your team is likely already using ChatGPT at work. Here is why an AI use policy matters now, what 2026 state rules say, and a simple checklist to start.
Law firm owner reviewing a printed profit and loss statement at a desk and marking key monthly lines
By Nettie Roos • August 24, 2026
Read your law firm P&L in ten minutes. The six lines to check top to bottom, the three numbers to track every month, and what a P&L will not tell you about cash.
A smartphone showing a two step login verification code beside a laptop on a bright desk.
By Nettie Roos • August 19, 2026
A plain English data security checklist for small businesses: the habits that actually protect you, plus who must follow the FTC Safeguards Rule.
By Nettie Roos • August 13, 2026
Got an IRS audit notice? Stay calm. Here are the steps to take, what records the IRS may request, and what it looks for. General info, not tax advice.
Calculator, eyeglasses, and pen on financial charts and papers on a desk.
By Nettie Roos • August 12, 2026
Most small law firms spend $300 to $1,200 a month on bookkeeping. See what drives the price, why trust accounting costs more, and how to find your number.
By Nettie Roos • August 9, 2026
The biggest shift any owner can make is learning to work on your business, not just in it. Here is what that looks like and simple ways to start this week.
Show More